Last updated: September 2026
This article is provided for informational purposes only and does not constitute legal, tax, or financial advice. Italian property law is complex and jurisdiction-specific. FrankVest strongly recommends engaging a qualified Italian notaio and a licensed commercialista before entering into any transaction. Information is accurate as of July 2026 but is subject to legislative change.
Table of Contents
- Why Marche Is Attracting Foreign Capital in 2026
- Legal Capacity and Reciprocity Requirements for Foreign Buyers
- The Italian Property Purchase Process: From Proposta to Rogito
- Due Diligence Specific to Marche: Planning, Seismic Risk, and Rural Land
- Taxes on Acquisition: Registration Tax, VAT, and Cadastral Charges
- Ongoing Property Taxes: IMU, TARI, and IVIE for Non-Residents
- Capital Gains Tax on Disposal
- Frequently Asked Questions
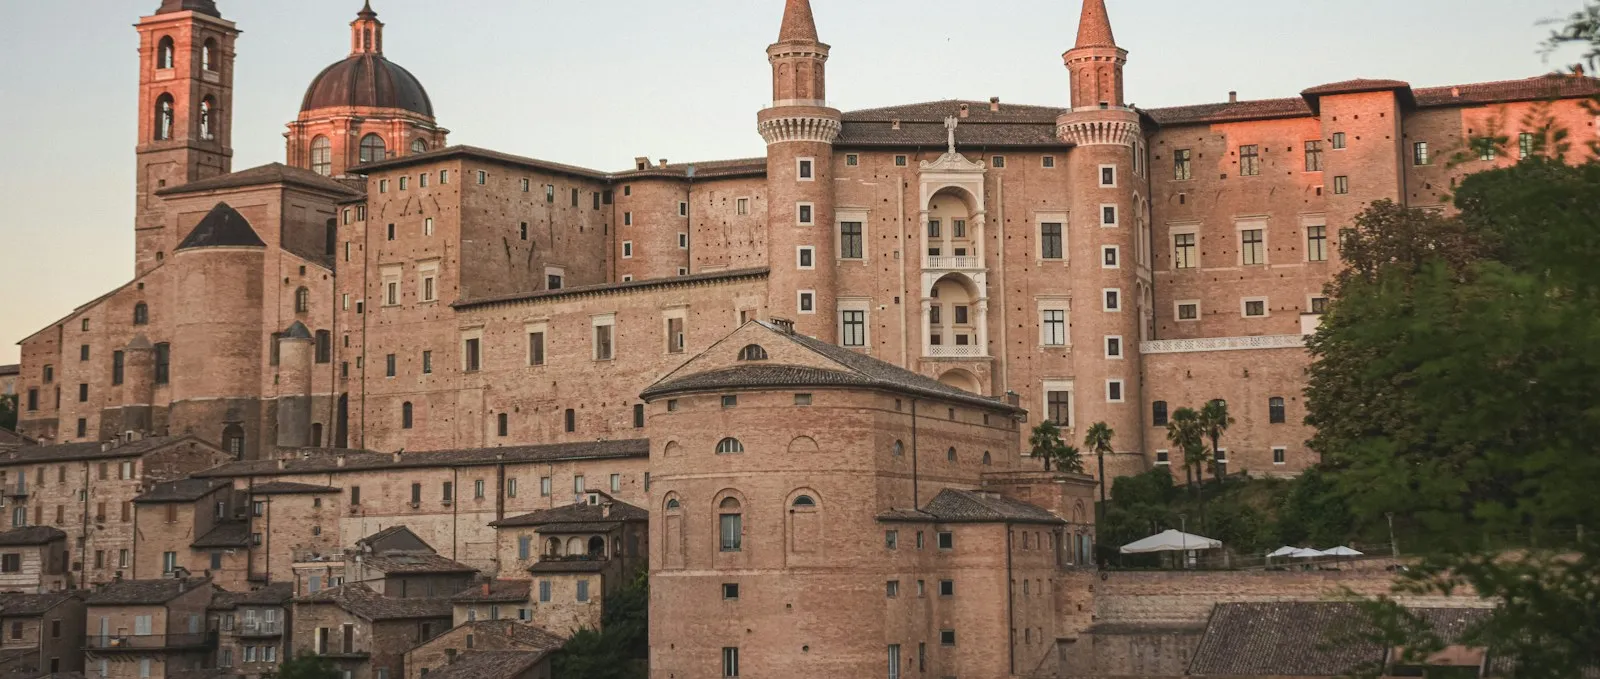
Foreign investors buying property in Marche, Italy are discovering one of Europe’s most undervalued real estate markets. Marche sits quietly between the Apennine mountains and the Adriatic coast, and for that reason it has long been overlooked by international investors who gravitated toward Tuscany, Umbria, or Puglia. That dynamic is shifting. Since the 2016 earthquake that severely affected the inland provinces of Macerata and Ascoli Piceno, sustained public investment in reconstruction and seismic upgrading, combined with historically low entry prices, has repositioned central Marche as one of Italy’s most compelling value plays. Coastal towns such as Pesaro, Senigallia, and Porto San Giorgio attract a younger, wealthier domestic and European demographic, while the hilltop towns of the interior — Urbino, Macerata, Fermo — offer a cultural depth that rivals Florence at a fraction of the cost.
For foreign investors, Marche presents a full-spectrum opportunity: primary residences, holiday homes, agriturismo conversions, rural masserie, and small hospitality businesses. Entry prices for habitable farmhouses with land remain between €80,000 and €250,000 in the interior provinces, with coastal renovated apartments trading at €2,500–€4,500 per square metre. This pricing gap relative to comparable Tuscan and Umbrian stock is narrowing, which is precisely why transactional volume from non-Italian buyers has increased measurably since 2023.
This guide provides the legal architecture foreign investors need before committing capital. It covers acquisition procedure, mandatory due diligence, tax exposure at every stage, structuring options, and the practical hazards that legal teams at FrankVest consistently encounter when acting for clients in this region.
1. Why Marche Is Attracting Foreign Property Investment in 2026
Marche’s investment case rests on three structural factors. First, post-earthquake reconstruction under the framework established by D.L. 189/2016 (converted into Law 229/2016) has unlocked substantial public grants and tax credits for owners willing to undertake seismic upgrading on properties in the so-called “crater” municipalities. Eligible works can attract contributions of up to 100% of reconstruction costs through the Agenzia per la Coesione Territoriale mechanism, provided the owner meets residency and documentation requirements. Foreign buyers are not automatically excluded, but the bureaucratic process requires competent local legal representation.
Second, Marche benefits from EU Cohesion Fund allocations for the 2021–2027 programming period targeting rural development, agriturismo infrastructure, and digital connectivity. Properties used for agriturismo or rural tourism can attract co-financed grants under the Regional Rural Development Programme (PSR Marche 2023–2027), administered through ASSAM (Agenzia Servizi Settore Agroalimentare delle Marche).
Third, the region has no single dominant market that distorts pricing the way Florence does in Tuscany. Investors willing to conduct methodical due diligence can still identify undervalued assets.
2. Legal Capacity and Reciprocity Requirements for Foreign Buyers
EU and EEA citizens buy property in Italy on the same terms as Italians. Other foreign citizens can buy if Italians are allowed to buy property in their country (the reciprocity condition, art. 16 of the preliminary provisions to the Civil Code), or if they live in Italy with certain residence permits. No prior authorisation is needed, but the condition is checked before the deed; for US and UK citizens it is treated as satisfied in practice. Canada currently bars most non-Canadians from buying homes in its cities and larger towns (census metropolitan areas and census agglomerations) and Australia currently restricts foreign purchases of established homes, so Canadian and Australian citizens who are not resident in Italy should have their position checked before signing an offer or paying a deposit. If you hold any other citizenship, have it checked by an Italian lawyer before you commit.
All foreign buyers must obtain a codice fiscale (Italian tax identification number) from the Agenzia delle Entrate or any Italian consulate abroad. This is a prerequisite for every stage of the transaction. Non-EU buyers who intend to take up residency must separately address visa status, which also determines the applicable tax treatment of the property.
3. The Italian Property Purchase Process: From Proposta to Rogito
The standard Italian acquisition sequence has three stages:
Proposta di acquisto (Letter of Intent/Offer): A preliminary offer, typically accompanied by a deposit of 1–3% of the purchase price. This is binding on the offeror once accepted and triggers estate agent commission obligations under Law 39/1989. Foreign investors should not sign any proposta without prior legal review.
Compromesso (Preliminary Contract, or Contratto Preliminare): Governed by Article 1351 of the Civil Code and Article 2645-bis of the Civil Code (which mandates transcription for preliminary contracts having as their object the conclusion of contracts transferring or constituting real rights over immovable property). The compromesso fixes price, assets, conditions precedent, and completion timeline. A deposit — typically caparra confirmatoria under Article 1385 of the Civil Code — of 10–30% is paid. If the buyer withdraws without justification, the deposit is forfeited; if the seller defaults, the buyer receives double the deposit. Transcription of the compromesso at the local Conservatoria dei Registri Immobiliari is highly advisable and protects the buyer against subsequent encumbrances registered against the property before completion.
Rogito (Final Deed of Sale): Executed before a notaio, who is legally a public official and whose function is distinct from the parties’ legal advisors. The notaio verifies title, checks for mortgages and judicial encumbrances (ispezione ipotecaria), ensures cadastral conformity, and registers the transfer. The notaio’s fee is no longer regulated by a fixed tariff following the liberalisation under D.L. 1/2012 (converted into Law 27/2012), but in practice typically ranges from 1–2.5% of the declared transaction value. Foreign buyers should appoint an independent avvocato or consulente in addition to — not instead of — the notaio.
4. Due Diligence Specific to Marche: Planning, Seismic Risk, and Rural Land
Marche’s particular geography creates due diligence requirements that go beyond the standard Italian checklist.
Seismic classification: Under the Ordinanza del Presidente del Consiglio dei Ministri (O.P.C.M.) 3274/2003 and the updated National Seismic Map (Mappa di Pericolosità Sismica) approved by D.M. 14/01/2008 (Norme Tecniche per le Costruzioni), virtually all of inland Marche falls within seismic zones 2 and 2A. Any structural intervention on a building in these zones requires prior authorisation from the Genio Civile (Regional Civil Engineering Office) under D.P.R. 380/2001 (the Consolidated Building Code, Testo Unico Edilizia), Articles 93–94. Failure to obtain this authorisation renders works technically abusive and can block future sale or rental.
Planning conformity (conformità urbanistica e catastale): The notaio is obliged under Article 29, paragraph 1-bis, Law 52/1985 (as amended by Law 122/2010) to verify that cadastral data matches the actual state of the property. However, in rural Marche, informal extensions, barn conversions, and outbuildings built without permits are common. A technical survey (perizia tecnica) by a geometra or ingegnere is essential before signing the compromesso.
Agricultural land pre-emption rights (diritto di prelazione agraria): Under Law 590/1965 and Law 817/1971, neighbouring farmers and tenants holding affitto agrario (agricultural lease) contracts hold a right of first refusal over agricultural land. If the property includes land designated as agricolo in the PGT or PRG (Piano Regolatore Generale) of the relevant Comune, the vendor must formally notify adjacent landowners and qualifying tenants before sale pursuant to Article 8 of Law 590/1965. Failure to comply allows a prelation action within one year of the transfer under Article 8, paragraph 5, Law 590/1965. This is one of the most frequently missed issues in rural Marche transactions.
5. Taxes on Buying Property in Italy: Registration Tax, VAT, and Cadastral Charges
Tax on acquisition is determined primarily by whether the seller is a private individual or a VAT-registered entity (impresa costruttrice), and whether the buyer qualifies for agevolazioni prima casa (first home reliefs) under Note II-bis to Article 1 of the Tariffa, Parte Prima, attached to D.P.R. 131/1986 (the Testo Unico dell’Imposta di Registro).
Standard rates (private seller, non-first home):
- Registration tax (imposta di registro): 9% of the cadastral value (valore catastale), pursuant to Article 1 of the Tariffa, Parte Prima, D.P.R. 131/1986
- Cadastral tax (imposta catastale): €50 fixed, pursuant to Article 10, D.Lgs. 347/1990
- Mortgage tax (imposta ipotecaria): €50 fixed, pursuant to Article 4, D.Lgs. 347/1990
First home relief (prima casa):
- Registration tax: 2% of cadastral value
- Cadastral and mortgage taxes: €50 each (fixed)
- Requires the buyer to establish Italian residency within 18 months of the deed, or to already be resident in the municipality of the property, pursuant to Note II-bis, paragraph 1, letter a), Tariffa, Parte Prima, D.P.R. 131/1986
Developer sale (VAT-applicable):
- VAT at 10% on residential units not classified as luxury (22% for luxury properties classified in cadastral categories A/1, A/8, A/9), pursuant to Article 10, paragraph 1, number 8-bis), D.P.R. 633/1972
- Registration, cadastral, and mortgage taxes at €200 each (fixed), pursuant to Article 40 D.P.R. 131/1986 and D.Lgs. 347/1990
Foreign buyers frequently overestimate the tax burden because they apply purchase price rather than cadastral value as the tax base. For older rural properties in Marche, the cadastral value can be as low as 20–35% of market price.
6. Ongoing Property Taxes in Italy: IMU, TARI, and IVIE for Non-Residents
IMU (Imposta Municipale Propria): Governed by Article 1, paragraphs 739–783, Law 160/2019 (Legge di Bilancio 2020), IMU is levied annually on all real property other than the owner’s main residence (abitazione principale). Non-resident foreign owners pay IMU on all Italian-held property. The standard base rate is 0.86% of the revalued cadastral value (rendita catastale × 1.05 × the relevant multiplier, which is 160 for residential property classified in cadastral groups A, C/2, C/6, and C/7, excluding A/10). Municipal authorities in Marche can adjust rates within a band of 0%–1.06% pursuant to Article 1, paragraph 754, Law 160/2019, or up to 1.14% where the municipality kept the former TASI surcharge (paragraph 755). A 50% IMU reduction applies to one dwelling that is neither let nor lent free of charge (comodato), owned by a non-resident who lives in another country where they were insured and receives a pension accrued under an international social-security convention with Italy (Law 178/2020, art. 1(48)). Parliament has been considering a reform of this relief, so check whether your pension qualifies and whether the rule has changed.
TARI: The waste collection tax is governed by Article 1, paragraphs 641–668, Law 147/2013 (Legge di Stabilità 2014) and is set by each municipality. It is generally €150–€600 per year for a residential property, depending on size and local tariffs.
IVIE (Imposta sul Valore degli Immobili all’Estero): Governed by Article 19, paragraphs 13–17, D.L. 201/2011 (converted into Law 214/2011), IVIE is relevant only if the investor is Italian tax resident and holds property outside Italy. It does not apply to a non-resident holding Italian property. Conversely, Italian-resident investors, including those on the flat tax for new residents (art. 24-bis TUIR, €300,000 a year for new residents from 2026), owe IMU but not IVIE on Italian assets.
7. Capital Gains Tax on Disposal
Under Article 67, paragraph 1, letter b), TUIR (D.P.R. 917/1986), gains on the sale of Italian real property held for less than five years are taxable as “redditi diversi” (miscellaneous income). The gain is calculated as the difference between the sale price and the original purchase price, increased by documented costs of acquisition and improvement pursuant to Article 68, paragraph 1, TUIR.
Tax rates:
- Substitutive tax (imposta sostitutiva) at a flat rate of 26%, elected at the time of the rogito before the notaio pursuant to Article 1, paragraph 496, Law 266/2005. This is the standard election for most non-resident sellers.
- Alternatively, the gain is included in ordinary IRPEF progressive rates under Articles 11 and 67 TUIR if the seller is Italian tax resident and the substitutive election is not made.
Properties held for more than five years are exempt from capital gains tax under Article 67, paragraph 1, letter b), TUIR. Inherited properties are exempt regardless of holding period, and so are homes used as the seller’s or their family’s main residence for most of the period owned; gains on building land are always taxable. A separate rule covers properties on which superbonus works (Article 119 D.L. 34/2020) were completed less than ten years before the sale: the gain is taxable (ordinary IRPEF or the optional 26% substitute tax) unless the property was inherited or used as the seller’s or family’s main residence for most of that period (Article 67(1)(b-bis) TUIR).
Frequently Asked Questions
Can foreign nationals legally buy property in Marche, Italy? Yes for EU and EEA citizens, and in practice for US and UK citizens. Other foreign citizens can buy if Italians may buy property in their country (reciprocity) or if they live in Italy with certain residence permits. Canadian and Australian citizens who are not resident in Italy should have their position checked before signing, because their own countries currently restrict foreign home buyers. There is no restriction specific to Marche. Every buyer first needs an Italian codice fiscale.
What are the stages of buying property in Marche, and what protects my deposit? The purchase follows three stages: the proposta di acquisto (a binding offer once accepted, usually with a 1–3% deposit), the compromesso or preliminary contract under Article 1351 of the Civil Code (which fixes price and terms and normally carries a caparra confirmatoria of 10–30% under Article 1385), and the rogito, the final deed executed before a notaio. If the buyer withdraws without justification the caparra is forfeited; if the seller defaults the buyer is entitled to double the deposit. Transcribing the compromesso at the local Conservatoria dei Registri Immobiliari, as permitted for preliminary contracts under Article 2645-bis of the Civil Code, protects the buyer against encumbrances registered before completion.
What taxes will I pay when buying a property in Marche? For a purchase from a private seller that is not a first home, registration tax is 9% of the cadastral value under D.P.R. 131/1986, with fixed cadastral and mortgage taxes of €50 each. First-home (prima casa) relief reduces registration tax to 2%, subject to establishing Italian residency in the municipality within 18 months. Where the seller is a VAT-registered developer, VAT applies at 10% (22% for luxury categories A/1, A/8, A/9) with fixed registration, cadastral, and mortgage taxes. Note that the tax base is the cadastral value, not the purchase price — for older rural Marche properties this can be as low as 20–35% of market value.
What due diligence is specific to buying rural or hill-town property in Marche? Marche’s geography adds requirements beyond the standard Italian checklist. Most of inland Marche sits in seismic zones 2 and 2A, so any structural intervention needs prior authorisation from the Genio Civile under Articles 93–94 of D.P.R. 380/2001; unauthorised works are technically abusive and can block a future sale. The notaio must verify that cadastral data matches the property’s actual state, but informal extensions and unpermitted outbuildings are common in the interior, so a technical survey (perizia tecnica) before the compromesso is essential. Where the property includes agricultural land, neighbouring farmers and qualifying tenants hold a pre-emption right under Article 8 of Law 590/1965 and Law 817/1971, and failure to notify them can support a prelation action within one year of transfer.
Do non-resident foreign owners pay ongoing property taxes in Marche? Yes. Non-resident owners pay IMU under Law 160/2019 on all Italian-held property other than a main residence, at a standard base rate of 0.86% of the revalued cadastral value, which municipalities in Marche can adjust within a 0%–1.06% band (up to 1.14% where the municipality kept the former TASI surcharge). A non-resident who receives a pension accrued under an international social-security convention with Italy may qualify for a 50% IMU reduction on one dwelling that is neither let nor lent free of charge; the relief may be reformed, so check whether it still applies. Owners also pay TARI, the municipal waste tax, typically €150–€600 per year. IVIE does not apply to a non-resident holding Italian property, as it concerns Italian tax residents who own real estate abroad.
Will I pay capital gains tax when I sell a property in Marche? It depends on how long you have held it. Under Article 67, paragraph 1, letter b), TUIR, a gain on a property sold within five years of acquisition is taxable as miscellaneous income, calculated as the sale price less the purchase price and documented acquisition and improvement costs. Non-resident sellers can elect a flat substitutive tax of 26% at the rogito before the notaio. Properties held for more than five years are exempt, as are inherited properties regardless of holding period and homes used as the seller’s or family’s main residence for most of the period owned. Gains on building land are always taxable, and a property on which superbonus works were completed less than ten years before the sale can be taxable (Article 67(1)(b-bis) TUIR).
Sources and further reading:
- Preliminary Provisions of the Civil Code — Article 16 (reciprocity)
- Italian Civil Code — Articles 1351, 1385, and 2645-bis (preliminary contract and deposit)
- D.P.R. 380/2001 — Consolidated Building Code, Articles 93–94 (seismic authorisation)
- Law 590/1965 and Law 817/1971 — Agricultural pre-emption rights
- D.P.R. 131/1986 — Consolidated Registration Tax Act
- D.Lgs. 347/1990 — Cadastral and mortgage taxes
- D.P.R. 633/1972 — VAT on new-build residential sales
- Law 160/2019 — IMU (municipal property tax)
- D.P.R. 917/1986 (TUIR) — Articles 67–68 (capital gains as redditi diversi)
- Agenzia delle Entrate — property purchase, first-home relief, and tax guidance